Oklahoma City Car Accident Lawyer
The adjuster who called you was friendly, sounded reasonable, and made an offer that did not come close to covering what you are actually facing. That is not an accident of tone. It is the job.
Our Oklahoma City car accident lawyers handle injury claims across Oklahoma County, and the first thing we do is answer a question most people never think to ask: how much insurance coverage actually exists in this crash, and whose policies can be reached. In Oklahoma that answer decides more cases than fault does.
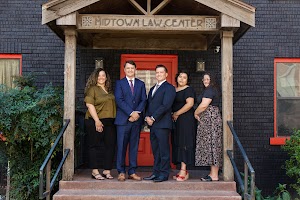
AP Injury Lawyers works out of 2248 NW 40th Street in Oklahoma City. We take crash cases involving cars, motorcycles, pedestrians, cyclists, impaired drivers, and rideshare vehicles.
Before you accept anything, call (405) 336-3000. We will tell you what coverage we can see and what it is likely worth. There is no charge for that call and we pick up at any hour.
Is There Actually Enough Insurance to Cover This?
Often, no. Oklahoma requires drivers to carry only $25,000 in bodily injury coverage per person, $50,000 per accident, and $25,000 in property damage. The Oklahoma Insurance Department confirms those limits in its own consumer guidance on auto insurance. A single ambulance ride and two days in a hospital can exhaust $25,000 before anyone has discussed lost income.
Those minimums were set decades ago and have not been raised. Medical costs have. That gap is the central problem in Oklahoma injury claims, and it is the reason a strong liability case can still produce a disappointing result if nobody goes looking for additional coverage.
Where the money can come from, in the order we usually check:
| Coverage source | When it applies |
| The at-fault driver’s liability policy | Always the first layer, often the smallest |
| Your own uninsured or underinsured motorist coverage | When the other driver has none or not enough |
| An employer’s commercial policy | If the at-fault driver was working at the time |
| A vehicle owner’s policy | When the driver did not own the car |
| A rideshare company’s policy | Uber and Lyft carry large limits when the app is on |
| Your medical payments coverage | Pays medical bills regardless of fault, if you bought it |
Most people never learn that four of those six exist. An adjuster is not going to mention them.
What If the Driver Who Hit You Had No Insurance?
Your own policy may cover it. Oklahoma insurers are required to include uninsured motorist coverage in every auto policy unless the customer signs a written rejection. If you never signed that rejection, you likely have it, even if you do not remember buying it.
Uninsured motorist coverage, usually shortened to UM, steps into the at-fault driver’s shoes. Underinsured motorist coverage, or UIM, covers the gap when the other driver carries a policy that is too small for the harm they caused. Under Oklahoma law the definition of an uninsured vehicle includes vehicles whose limits are less than the amount of the claim, and vehicles whose insurer has gone insolvent. Hit and run drivers are covered too.
The Oklahoma Insurance Department explains the offer and rejection process on its uninsured motorist page, and states plainly that Oklahoma’s share of uninsured motorists is among the highest in the nation.
Two practical points:
- Pull your declarations page, not your ID card. The UM limit is listed there. If you cannot find it, we will request it.
- A UM claim is made against your own insurer, and your own insurer will defend it like any other adversary. Being their customer for fifteen years does not change how the claim gets evaluated.
The state also runs the Uninsured Vehicle Enforcement Diversion program, which uses automated plate readers to identify uninsured vehicles and route owners into coverage instead of court. It is described on the Oklahoma District Attorneys Council site. Helpful policy, but it does not put coverage on the car that hit you last month.
If you do not know whether you carry UM, call (405) 336-3000 and we will find out today.
How Long Do I Have to File a Car Accident Claim in Oklahoma?
Two years from the date of the crash for a personal injury claim, under Oklahoma’s general limitations statute. Property damage runs on the same two year clock. File after that and the case is over regardless of how clear the other driver’s fault was.
Two situations shorten it, and both are easy to miss.
If a city, county, or state vehicle was involved, the Governmental Tort Claims Act applies instead, and the window to give written notice is one year rather than two. Public transit buses, municipal work trucks, and school vehicles all fall in this category, and drivers often do not realize it until they read the police report.
If the crash resulted in a death, the claim runs under Oklahoma’s wrongful death statute rather than the injury statute, and the person who can file is not necessarily the surviving family member. That is explained on our Oklahoma City wrongful death page.
Waiting also costs evidence, which matters more than the calendar. Business surveillance footage overwrites in days. Vehicles get repaired or scrapped. Skid marks wash away in the first Oklahoma thunderstorm.
The Insurer Will Argue You Were Partly at Fault
Expect it, and know that being partly at fault does not end an Oklahoma claim. Your award drops by your share of the blame, and it only disappears if your share climbs past the other driver’s.
That threshold is why the recorded statement matters so much. Nudging you from 40 percent responsible to just over half does not trim the claim. It erases it, and the adjuster asking the questions knows exactly where that line sits.
Listen for the shape of it. The questions that sound like small talk are the ones doing the work:
- "How fast would you say you were going, roughly?"
- "You didn't see him until the last second?"
- "Were you feeling okay that morning?"
- "You've had that shoulder bother you before, right?"
Other things get used the same way. Saying “I’m fine” at the scene. A social media post showing you at a birthday party. Any sentence that begins with “I probably should have.”
You are not required to give the other driver’s insurer a recorded statement. Declining one is not evidence of anything, and it cannot be held against you later.
Reviews From Our Clients


I always felt like they genuinely cared about me and my recovery, not just my case. They took great care of me from start to finish, and I never felt like I was going through everything alone. If you’ve been in a car accident and need someone you can trust to fight for you while treating you with kindness and respect, I highly recommend them.

From start to finish, working with Austin and his team was an exceptional experience. The entire process was smooth, organized, and stress-free. They handled everything, so we never had to wonder what was happening or what came next. Communication was 10/10 — we were always kept informed and any questions we had were answered promptly.
Most importantly, the outcome exceeded our expectations. We couldn’t be happier with the level of professionalism, responsiveness, and care we received. Highly recommend AP Injury Lawyers to anyone looking for a team that truly delivers.
Austin earned my trust and my case lending me a glimpse of insight to the culture he had created for his law firm. I signed that day, and eight days later he called me to say that the insurance company had agreed to pay policy max. I’m happy with Austin and his crew for doing what I alone had failed to do: bring timely acceptable closure to a tinder issue. I highly recommend APInjury Lawyers, because Austin is at the helm, and I trust him.
Humbly, David Strickland


Also, a great outcome! I worked directly with Tripp, who was kind, supportive, and knowledgeable throughout the entire process. He consistently checked in with me, explained everything clearly, and made sure I understood each step along the way.
I had never been in a situation like this before, and they truly made the process feel easy and stress-free. They handled everything and helped bring me peace of mind during a difficult time. I’m so grateful for their help and would absolutely recommend them to anyone needing an injury attorney.
Why Your Medical Bills Are Worth Less Than the Number on Them
If a hospital billed $60,000 and your health insurer settled it for $14,000, the jury generally hears $14,000. The difference, called a write-off, disappears from the claim.
There is a significant exception. Where a lien has been filed, bills above the amount paid are admissible up to the amount of the lien. Under Oklahoma’s hospital lien statute, a hospital can assert a lien against your recovery for reasonable and necessary charges, and that lien is expressly inferior to your attorney’s lien.
The practical consequence for you:
- How your treatment is billed, and whether a provider takes a lien instead of billing health insurance, directly changes what your case is worth.
- Those decisions get made in the first weeks of treatment, usually by someone who is not thinking about your claim.
- Sorting it out after the fact is much harder than setting it up correctly at the start.
This is the single strongest argument for calling a lawyer early rather than after treatment ends.
How Do I Get a Copy of My Oklahoma Crash Report?
It depends on which agency worked the crash. A collision investigated by the Oklahoma Highway Patrol or reported to the state goes through Service Oklahoma. A collision worked by Oklahoma City police inside city limits goes through the department’s records unit.
For state records, Service Oklahoma publishes an official Collision Request for Records form. The fee is $7.00, or $10.00 certified. Requests are accepted by mail or in person only, not by email, and reports can take up to 30 days to appear in the system.
For city crashes, requests go through the Oklahoma City Police Records Unit at 700 Colcord Drive.
Separately, Oklahoma law requires a driver to notify law enforcement immediately when a crash causes injury or death. If damage exceeds $300 and the matter is not resolved within six months, a written report to the Department of Public Safety is required.
We pull reports for our clients as a matter of course. If you are handling it yourself, request it early, because the report is what the adjuster will anchor to.
What Working With This Firm Looks Like
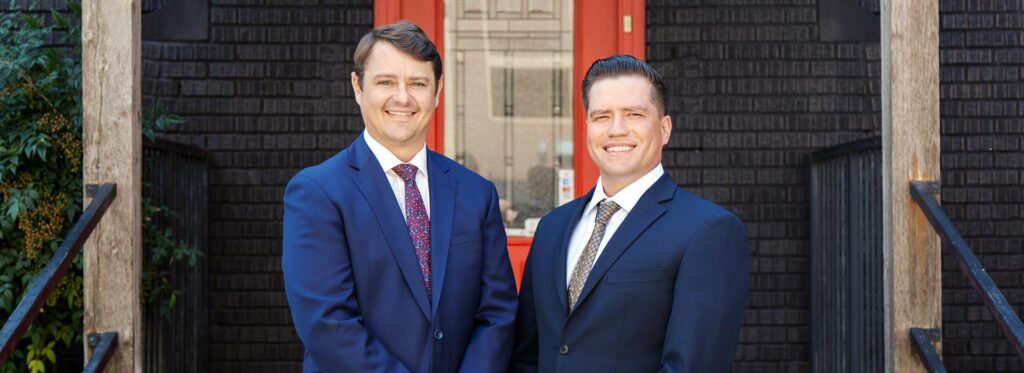
Austin S. Pieratt founded this firm after law school at Oklahoma City University, and the practice has been built around Oklahoma claims rather than run as a satellite of an out of state operation. Clients deal with the lawyer, not a rotating queue of case handlers, and the phone is answered at any hour.
The firm’s Google rating currently sits at 5.0 across several hundred reviews.
We handle car, motorcycle, pedestrian, bicycle, rideshare, and impaired driver crashes. We do not take medical malpractice, product liability, or construction site cases, and we will say so on the first call rather than after you have signed.
Frequently Asked Questions
Should I accept the first offer from the insurance company?
Almost never, and not before you know your final medical picture. A first offer is typically made while treatment is ongoing, which means it cannot account for care you have not had yet. Once you sign a release, the claim is closed permanently, even if you need surgery three months later. Have the offer reviewed before you respond.
Will my own insurance rates go up if I make an uninsured motorist claim?
Making a claim for a crash you did not cause should not raise your premium in the way an at-fault claim would. Oklahoma insurers rate on fault and loss history. That said, policies and carriers vary, so ask your agent for your carrier’s specific rule. Do not let the worry stop you from claiming coverage you already paid for.
Do I have a case if I did not go to the hospital right away?
Possibly, but the delay will be used against you. Insurers treat a gap between the crash and the first medical visit as evidence you were not really hurt. It is not proof of anything, and soft tissue injuries commonly worsen over 48 to 72 hours. Get evaluated now and be straightforward about the timeline rather than adjusting it.
What does a car accident lawyer charge in Oklahoma City?
Nothing out of pocket, ever. There is no retainer and no hourly billing. The fee is a percentage of what is recovered, and if nothing is recovered there is no fee. Ask any firm you talk to whether the percentage is calculated before or after case costs come out, because that single detail changes what you actually receive.
Find Out What Coverage You Actually Have
Most people call a lawyer to find out if they have a case. The more useful question in Oklahoma is whether there is enough insurance behind the case to matter, and that is not something you can determine from the other driver’s ID card.
We will look at every policy that could apply, including your own, and tell you where you stand. If the answer is that you do not need us, we will say that too.
Call or text (405) 336-3000. AP Injury Lawyers, 2248 NW 40th Street, Oklahoma City, OK 73112. Available 24 hours.